Krosos FIRE Calculator: First Look at the Free 50-Year Wealth Forecasting Tool
By Day Zero Guides Editorial · How we produce guides
Some links in this guide are affiliate links. If you sign up through them, Day Zero Guides may earn a commission at no extra cost to you. This never affects which products we cover or what we say about them. See our affiliate disclosure for details.
What Krosos FIRE Calculator Actually Does
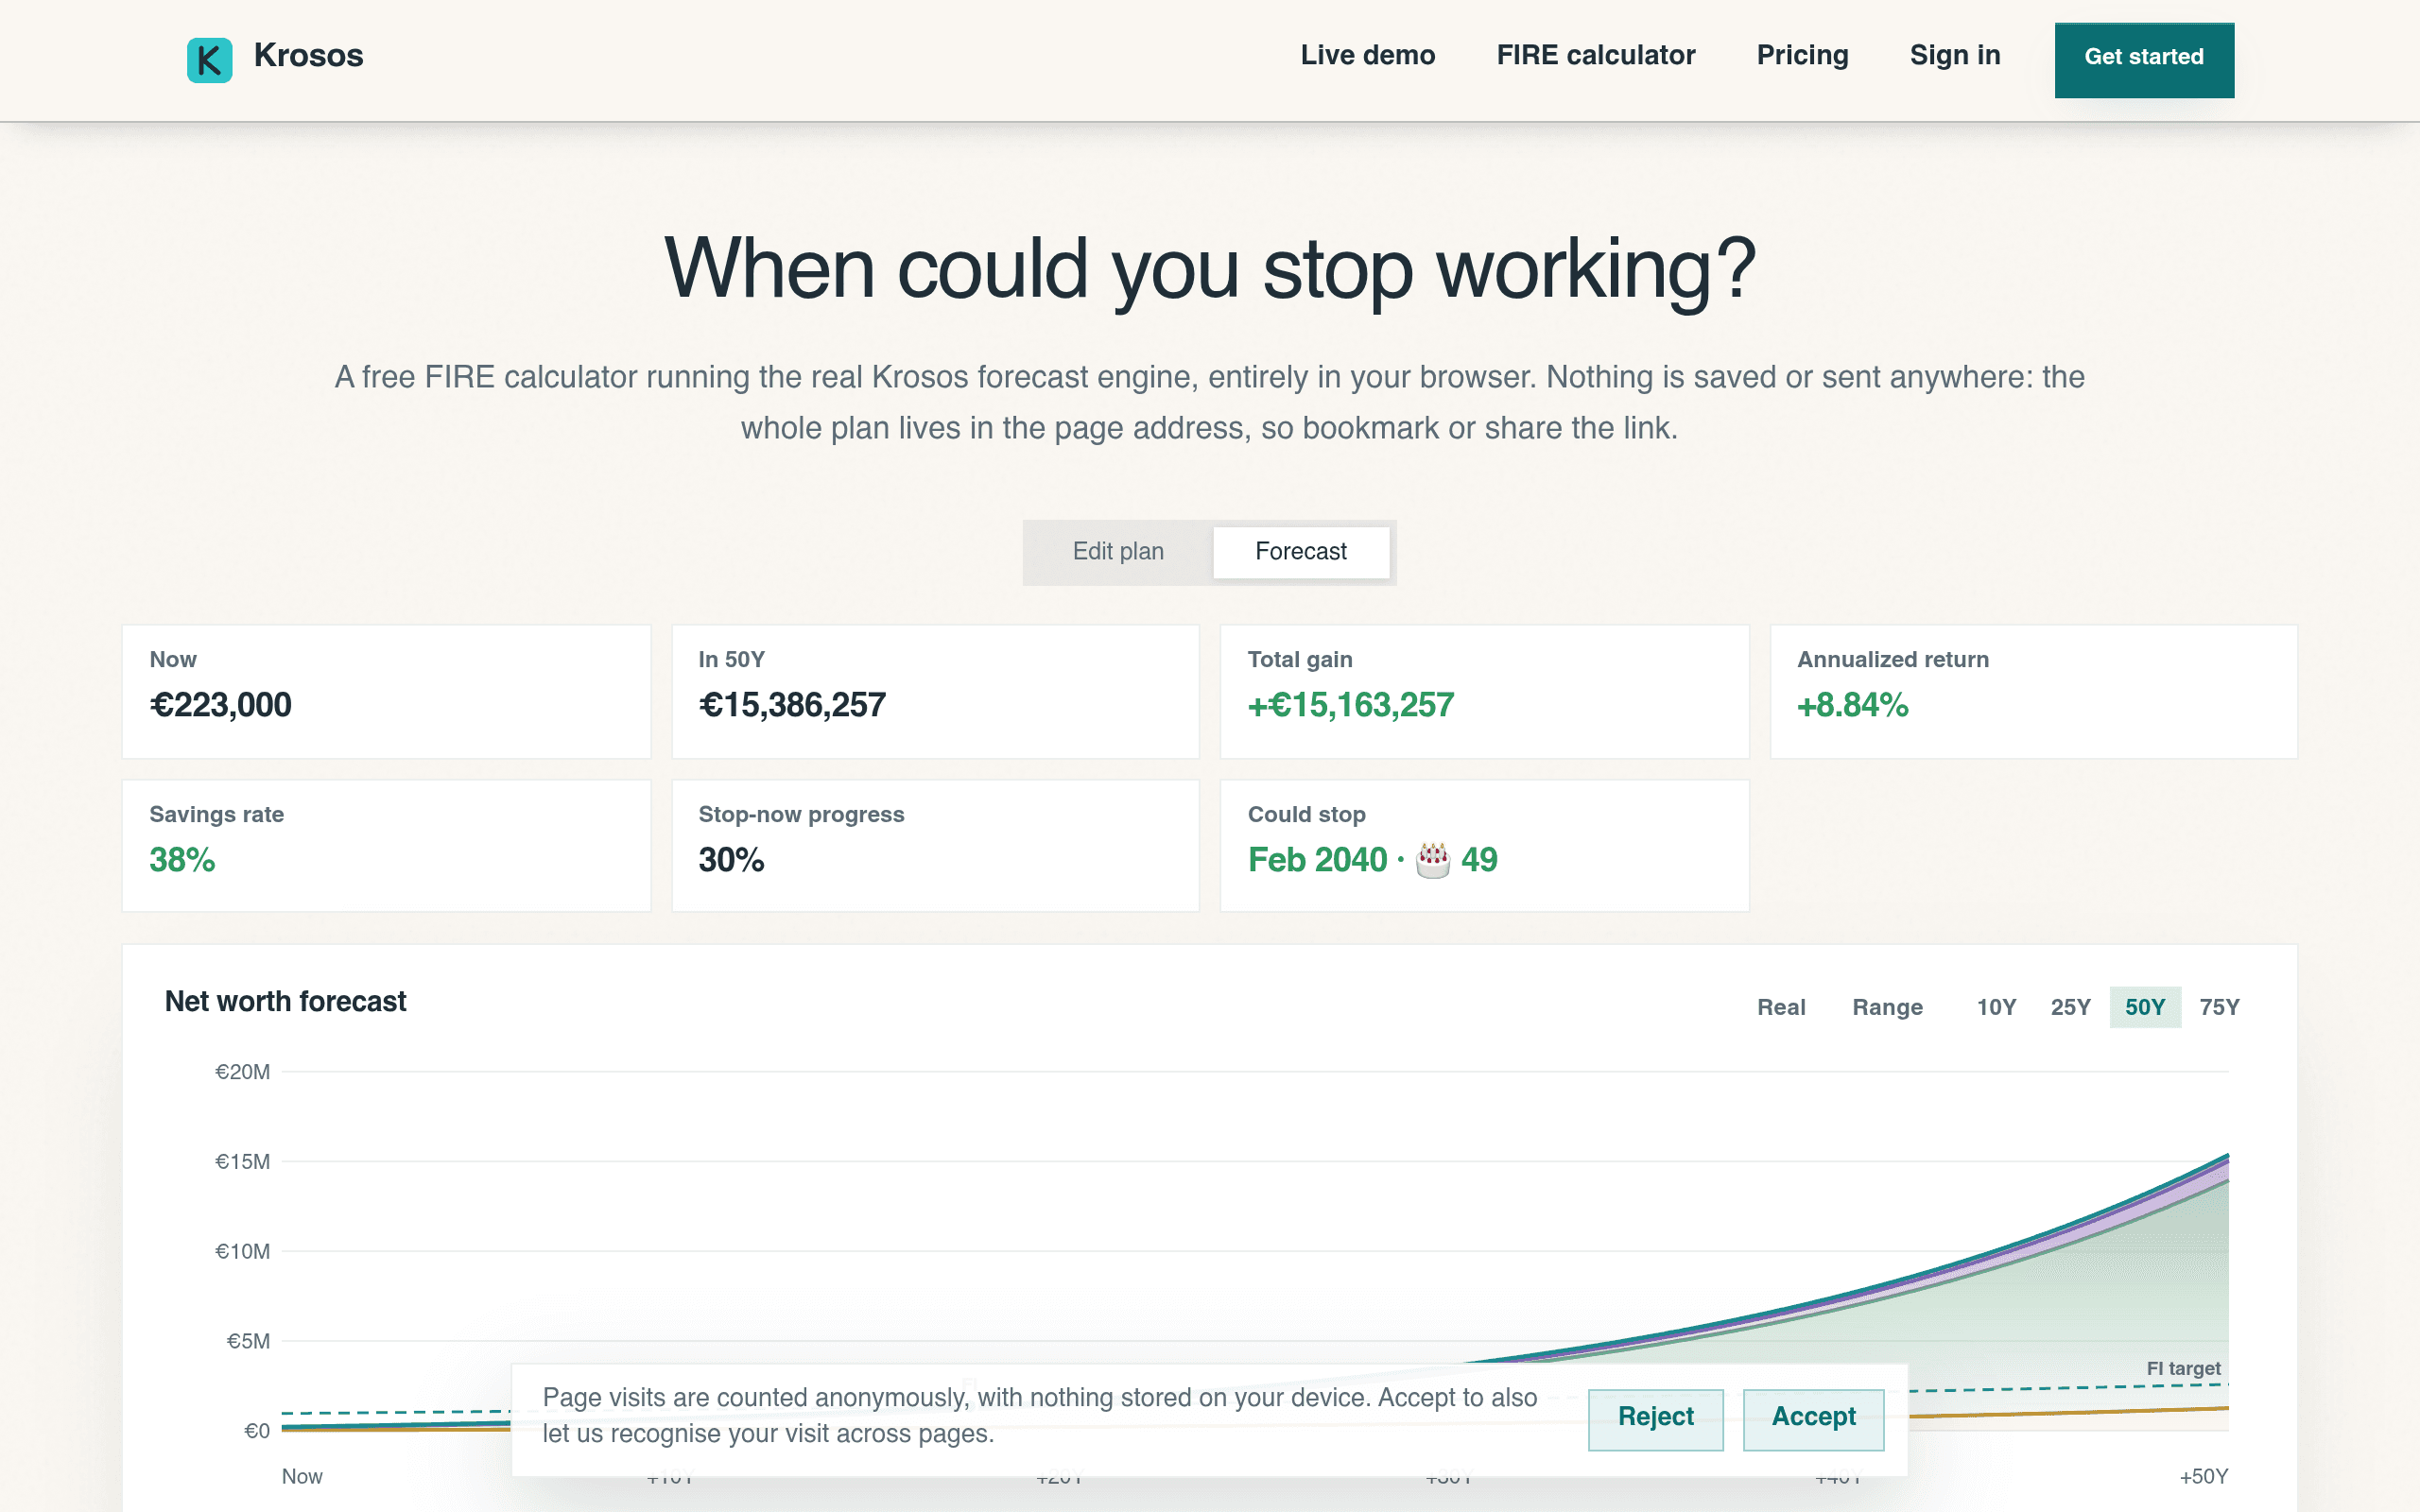
Krosos FIRE Calculator (found at krosos.com/forecast) is a browser-based tool that models your path to financial independence by projecting portfolio growth, savings rates, and tax drag across a 50+ year horizon. Unlike most retirement calculators that give you a single "you'll retire at 62" number, Krosos builds out a full trajectory year by year, letting you see how contribution changes, market return assumptions, or withdrawal rates shift your FIRE date.
The standout technical detail: results are shareable via a URL, and Krosos doesn't store your data on a server. Your inputs get encoded into the link itself, so when you share a forecast with a partner, a financial advisor, or a subreddit thread, you're not creating an account on someone's database — you're just passing a link that reconstructs the calculation client-side. For a tool dealing with income, savings, and net worth figures, that's a meaningfully different privacy posture than most fintech calculators.
Who This Is Actually For
This isn't a budgeting app or a net-worth tracker. It's a forecasting instrument for people who already have a handle on their numbers and want to stress-test assumptions. Concrete scenarios where it's useful:
- A 34-year-old software engineer with a $180K portfolio wants to know whether bumping their savings rate from 25% to 35% moves their FIRE date from 52 to 47 — and how sensitive that is to a 6% vs. 7% real return assumption.
- A couple planning a Coast FIRE move who want to model what happens if they stop contributing to retirement accounts entirely at 40 but let existing investments compound for another 20 years before touching them.
- Someone deciding between a Roth conversion ladder and traditional withdrawals who wants a rough sense of how tax impact compounds over a multi-decade drawdown, not just a single-year estimate.
- A person comparing two job offers with different savings capacities who wants a shareable link to send both scenarios to a spouse without emailing spreadsheets back and forth.
It is not built for people who want automatic account aggregation, daily net-worth tracking, or investment management — for that, you're back to Personal Capital or Wealthfront territory.
Pricing: What's Free Today vs. What's Coming
The forecasting tool at krosos.com/forecast is free, full stop, with no account creation or paywall on the core projection features. Krosos has signaled a premium tier — described as a "forecast engine" with live syncing (presumably connecting to actual brokerage or bank data rather than manual entry) — but pricing for that tier isn't published yet. If you're evaluating this today, treat it as: free forever for manual, one-time or occasional forecasting; unknown cost for anyone who wants ongoing automated updates tied to live account balances.
That's a meaningful caveat. If your use case is "I want to check my FIRE number twice a year," the free tool covers you completely. If you want a dashboard that updates itself as your portfolio moves, you're currently in wait-and-see territory on what that costs.
How It Compares
| Krosos FIRE Calculator | Personal Capital (Empower) | Wealthfront | NewRetirement | |
|---|---|---|---|---|
| Price | Free (premium live-sync tier pricing TBD) | Free planning tools; requires linking accounts, upsells to paid wealth management (0.49%–0.89% AUM) | Free financial planning tools; paid robo-advisor at 0.25% AUM | Free basic plan; PlannerPlus subscription ~$120/year |
| Data model | Manual input, no server storage, results shareable via URL | Requires linking real bank/brokerage accounts via Plaid | Requires linking accounts or Wealthfront brokerage | Manual input or account linking, cloud-stored profile |
| Forecast horizon | 50+ years, year-by-year trajectory modeling | Retirement planner tool, shorter-horizon emphasis, tied to net worth dashboard | Path-style projections tied to their investment products | Long-horizon retirement modeling, detailed tax/Social Security inputs |
| Best for | Quick, private, scenario-based FIRE math without linking accounts | People who want net worth tracking + investment fee analysis alongside planning | People already investing with or considering Wealthfront's robo-advisor | People wanting deep customization (healthcare costs, Social Security timing, part-time work) |
| Privacy approach | No account, no server storage, data lives in the URL | Requires account linking, data stored by Empower | Requires account, tied to Wealthfront ecosystem | Requires account for saved plans |
The Honest Trade-offs
The no-account, no-server-storage design is genuinely refreshing if you've ever hesitated to link your actual brokerage login to a free calculator just to see a number. But it cuts both ways: because Krosos doesn't store your data, you're responsible for saving your own share link if you want to revisit a forecast later. There's no dashboard to log back into, no automatic tracking of how your actual portfolio is performing against the projection.
Compared to NewRetirement, which lets you model granular details like Social Security claiming age, part-time "barista FIRE" income, or healthcare cost inflation separately, Krosos's current free tool appears more streamlined — better for a fast gut-check than a full retirement plan with dozens of levers. Compared to Personal Capital and Wealthfront, you lose automatic account aggregation entirely, which is either a dealbreaker or a feature depending on how much you want a third party looking at your linked accounts.
Should You Try It Today
If you want a fast, private, no-signup way to answer "at my current savings rate and a reasonable return assumption, when do I hit FIRE, and how does that change if I save more or retire earlier," this is worth 10 minutes right now — it's free and there's no account wall. If you want ongoing tracking tied to real account balances, wait for pricing on the premium live-sync tier, or stick with Personal Capital or Wealthfront in the meantime, since those already offer account linking today rather than as a forthcoming feature.